

Entity return opens
Partnership or S corp.
A tied month feeds the estimate.
Form 7004 if the return is not ready.
Free file-or-pay check
Four taps. A filing request is not time to pay.
The form is short. The number is not.
The form takes a few minutes. The number on it takes a closed month, and then the return those months are for.
Steven Palmieri, Tax CFO.
An extension is a sign the month before the deadline was open. The Tax CFO closes it every month, so the number is known before the form is due, the payment goes with the original day, and October is a quiet month instead of a second deadline. If you do need one this year, we file it tonight and close the month tomorrow.
Talk about the date
The company return's day comes in mid-March, a month before the household return. Extending one does not extend the other.
Click to open ›Tap to open ›
The extended household return lands in mid-October. If the month is still open then, the extension bought nothing.
Click to open ›Tap to open ›
A federal extension does not move a state report. Most states keep their own day, and some keep a second form.
Click to open ›Tap to open ›
The payment was due on the original day. An extension moves the paper, not the balance, and interest starts anyway.
Click to open ›Tap to open ›
The figure has to come from a tied month.
Click to open ›Tap to open ›File with a number you can support.
Click to open ›Tap to open ›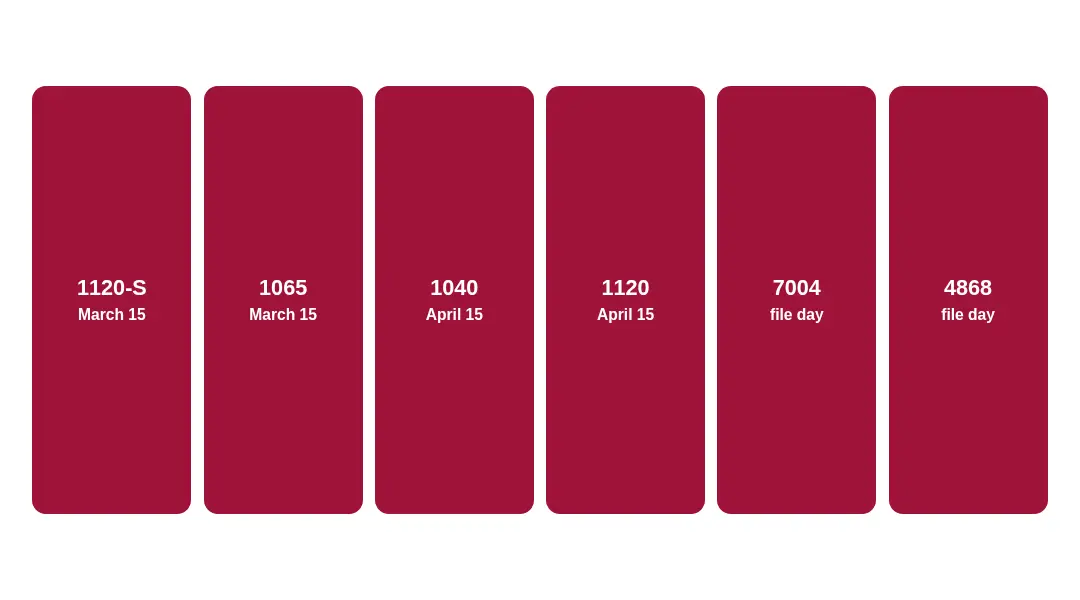

Steven and his team, with Steven Palmieri as Tax CFO and the Entrepreneur's CFO, close the month and prepare the return from it.
People arrive here wanting a date, and the date is real. A personal return is due in the middle of April. A timely extension carries that filing out to the middle of October. A partnership and an S corp start earlier, in the middle of March, and a timely extension carries those filings to the middle of September. A calendar year C corp follows the April start and the October end. If the fifteenth lands on Saturday, Sunday, or a federal holiday, filing waits until the next open weekday. That is the whole calendar in one breath, and it is the easy breath.
The form itself is short. An individual uses Form 4868. Most entities use Form 7004, with a code for the return being extended. You can file the individual one electronically, by mail, or by paying online and marking the payment as an extension payment. The IRS confirms an electronic request. A mailed form is not confirmed unless something is wrong with it. None of that takes an afternoon.
What takes the afternoon is the number the form asks you to stand behind, an estimate of the tax for the year. A tidy figure chosen because it felt about right is a different filing from a figure you can walk back to a month that ties to the bank. If anyone asks later, you will know which kind you sent. The pages under the tiles are the long version of that difference.
Filing can move. The payment date does not. That split is why the form is still worth filing when the money is short. Interest on an unpaid balance starts from the original due date, extension or not. A timely extension takes the filing penalty off the table for the extension window. The paying penalty keeps running on whatever remains unpaid.
The filing penalty is 5 percent of the unpaid tax for each month or part of a month, up to 25 percent. The paying penalty is half a percent a month, also up to 25 percent. When both apply in the same month, the filing rate for that month comes down by that half a percent. A timely extension is the thing that keeps the faster rate from running. Sending nothing with the form is allowed. Pretending the balance is zero is a different choice.
If a return is more than 60 days late and there was no valid extension, the filing penalty has a minimum. For a return due after 31 December 2025 that minimum is 525 dollars or the entire underpayment, whichever is less. Those rates are the ones on the IRS pages for failure to file and failure to pay. They are general. None of those rates is a bill computed for your company. The page about paying sets the two rates next to each other without turning them into a scare.
March is the entity week for a partnership and an S corp. April is the personal return, and it is also the C corp. June is the next individual estimate, and it does not care that a federal extension was filed. September brings the extended entity returns back. October brings the extended personal return, and it ends there. The four quarterly estimates keep the dates they already had. Neither extension form slides them.
A state that taxes income publishes its own return, and that return is not a copy of Form 4868. A page that tells every reader to file one state extension is describing a filing some states do not have. A balance from wages, a rental, or a K-1 sourced in a second state is a different question, and it should be named as that state rather than invented into a form the home state does not publish.
The federal weekend rule is the same wherever you file. If the fifteenth lands on Saturday, Sunday, or a federal holiday, the filing moves to the next open weekday. The payment date does not take a holiday of its own. Interest on an unpaid balance still starts from the original due date. We carry that rule on the same calendar as the two forms, and we do not print a private weekday that disagrees with the IRS page for the year.
March belongs to a partnership or an S corp on a calendar year. The month that ties is the one that can feed the estimate. Form 7004 belongs on that day if the return will not be ready. April belongs to an owner, a joint return, or a disregarded company riding on that return. The company extension does not cover this one. Form 4868 keeps the personal filing inside the rules while a K-1 is still out.
The next estimate, often the middle of June for an individual, stays where it was. A federal extension leaves that estimate alone. We carry it on the same calendar as the filing dates, and we size it from the last month that ties to the bank. September brings the extended entity return for the partnership or S corp that moved in March. The summer is for closing the months, not for hoping. The K-1 is born here, and the personal return is still waiting on it.
October ends the extended personal return for the owner whose April form bought these months. There is no ordinary second extension after this day. October is also when a choice can still change the year that has not ended. The morning after any of those days, the return still has to be built from a month the bank supports. Filing the return stops the faster penalty. Paying what you can comes next.
The company week and the household week are two filings. Extending one does not extend the other. The October day is the filing the spring form bought, and an open month then means the extra time bought paper and not a number. A state report, where the state has one, keeps its own day. If the filing day is a Saturday, a Sunday, or a federal holiday, it does not stay on that day, and it does not wait for a Monday that the IRS page did not name.
The month before a deadline is the month that decides whether the form is a rescue or a routine. We close that month on a calendar, so April is a payment and October is a filing, not a second scramble.
Extending it does not extend the household return. An open month means the extra time bought nothing. Most states keep their own day and their own form. If the fifteenth is a weekend or a federal holiday, filing moves to the next open weekday. A round figure chosen to look calm is a different filing from one built off a month that ties. Once the day has passed, file with the best number you can support, then pay what you can.
The hard part of a deadline was never the clock. It is being the only person who could explain the figure if anyone asked. Once a month is closed, somebody else can write the estimate onto the form and you can see the line it came from. That is a quieter April. The same people who keep the books can prepare the return the extension is buying time for, and they can talk through October while a choice can still change the year.
When the writing is signed it names Steven Palmieri as Tax CFO, with the Entrepreneur's CFO beside that role, and it covers the books, a monthly close, reconciliations, statements, reports, payroll setup with the company you already pay, and the return the extra months are buying time for. The extension has to agree with those months.
If your month is already closed, you already know how the entity is taxed, and the date was the only thing missing, go and file the extension. That route does not require a conversation with us. The pages here are written so that route works without one. Where the work starts earning its keep is when the number cannot be produced yet.
No. The payment stays on the original due date. What changes is which penalty is in play, and the filing penalty is the expensive one. The arithmetic lives on the page about paying.
Most business returns use Form 7004. A personal return uses Form 4868. A limited liability company does not get a form from its name. It gets a form from the tax election on file. That check comes before any date is memorized.
A low estimate can leave a balance that starts the paying penalty. It does not, by itself, erase a timely extension. The estimate page walks the build without pretending the number can be perfect in March.
Yes, when both are in play. An S corp extension does not extend the shareholder's personal return. The K-1 often arrives inside the personal extension window, which is why the order matters. Company first, in March. Personal in April, even if the K-1 is not in hand.
There is no ordinary second extension for an individual return. After that date the filing is late. Disaster relief and a narrow announcement are read from the IRS page for that year rather than assumed. The October page says what the next morning looks like, without a countdown.
The extension can still be filed. The estimate should be built from the last month you trust, with the open months labeled as open. An unreconciled feed is a reason to keep the unidentified pile out of the figure, or to show it as a range you can defend. Leaving the form unfiled does not make the open months safer.
File the return with the best number you can support, then pay what you can. Waiting to file until you can pay in full leaves the faster penalty running on top of the slower one. Once the return is in, only the paying penalty and interest remain on the unpaid part. A missed date is still a filing problem. It is not a collections engagement. This practice does not negotiate a balance.
The IRS does not charge for the form. The money in the decision is the estimate you certify and the penalty you avoid by filing on time. This page does not publish a fee for the practice. A number made up for the screen would be theatre. A price belongs on the written scope, which is why this page prints none.
Income on a K-1 can show up on a personal return without a distribution ever leaving the company. The extension does not fix that mismatch. It only buys the time to compute it from a closed set of books. Owners who wait for the K-1 and then discover the personal return was never extended have spent the summer feeling finished and the fall finding out they were not.
The same habit that makes the estimate explainable makes the next year smaller. Quarterly estimates should track the year you are actually having, rather than last year's bill split into four even hopes. By October there is still time to fund a retirement plan, to time a purchase, or to decide that a choice should wait. That conversation is ordinary work. It is not a product with a private name.
Read the order of the two filings, how a partial year becomes a number, and which dates are carried here. The two jobs that go elsewhere are a balance someone wants negotiated, and any statement a lender wants an assurance cover on.